2026 marks the largest expansion of HSA eligibility since 2003. Learn how the new ACA Marketplace rules allow more families in NC & SC to access the "Triple Tax Advantage" of Health Savings Accounts to lower their taxable income and save for medical costs.
The 2026 HSA Expansion: A Smart Way to Save
For years, HSAs were a niche product. In 2026, the law has changed to make these powerful tax-savings tools accessible to more people than ever before. If you’ve ignored HSAs in the past, it’s time for a fresh look through a smarter lens.
The Largest Eligibility Expansion Since 2003
We haven't seen a move this significant since HSAs were first established in 2003. This isn't just a minor update; it's a fundamental change in how the government encourages us to save for our own healthcare future.
Harness the Triple Tax Advantage
An HSA is the only financial vehicle that hits a "home run" on taxes. Most investments tax you on the way in, the way out, or both. The HSA is designed to keep your money in your pocket at every stage.
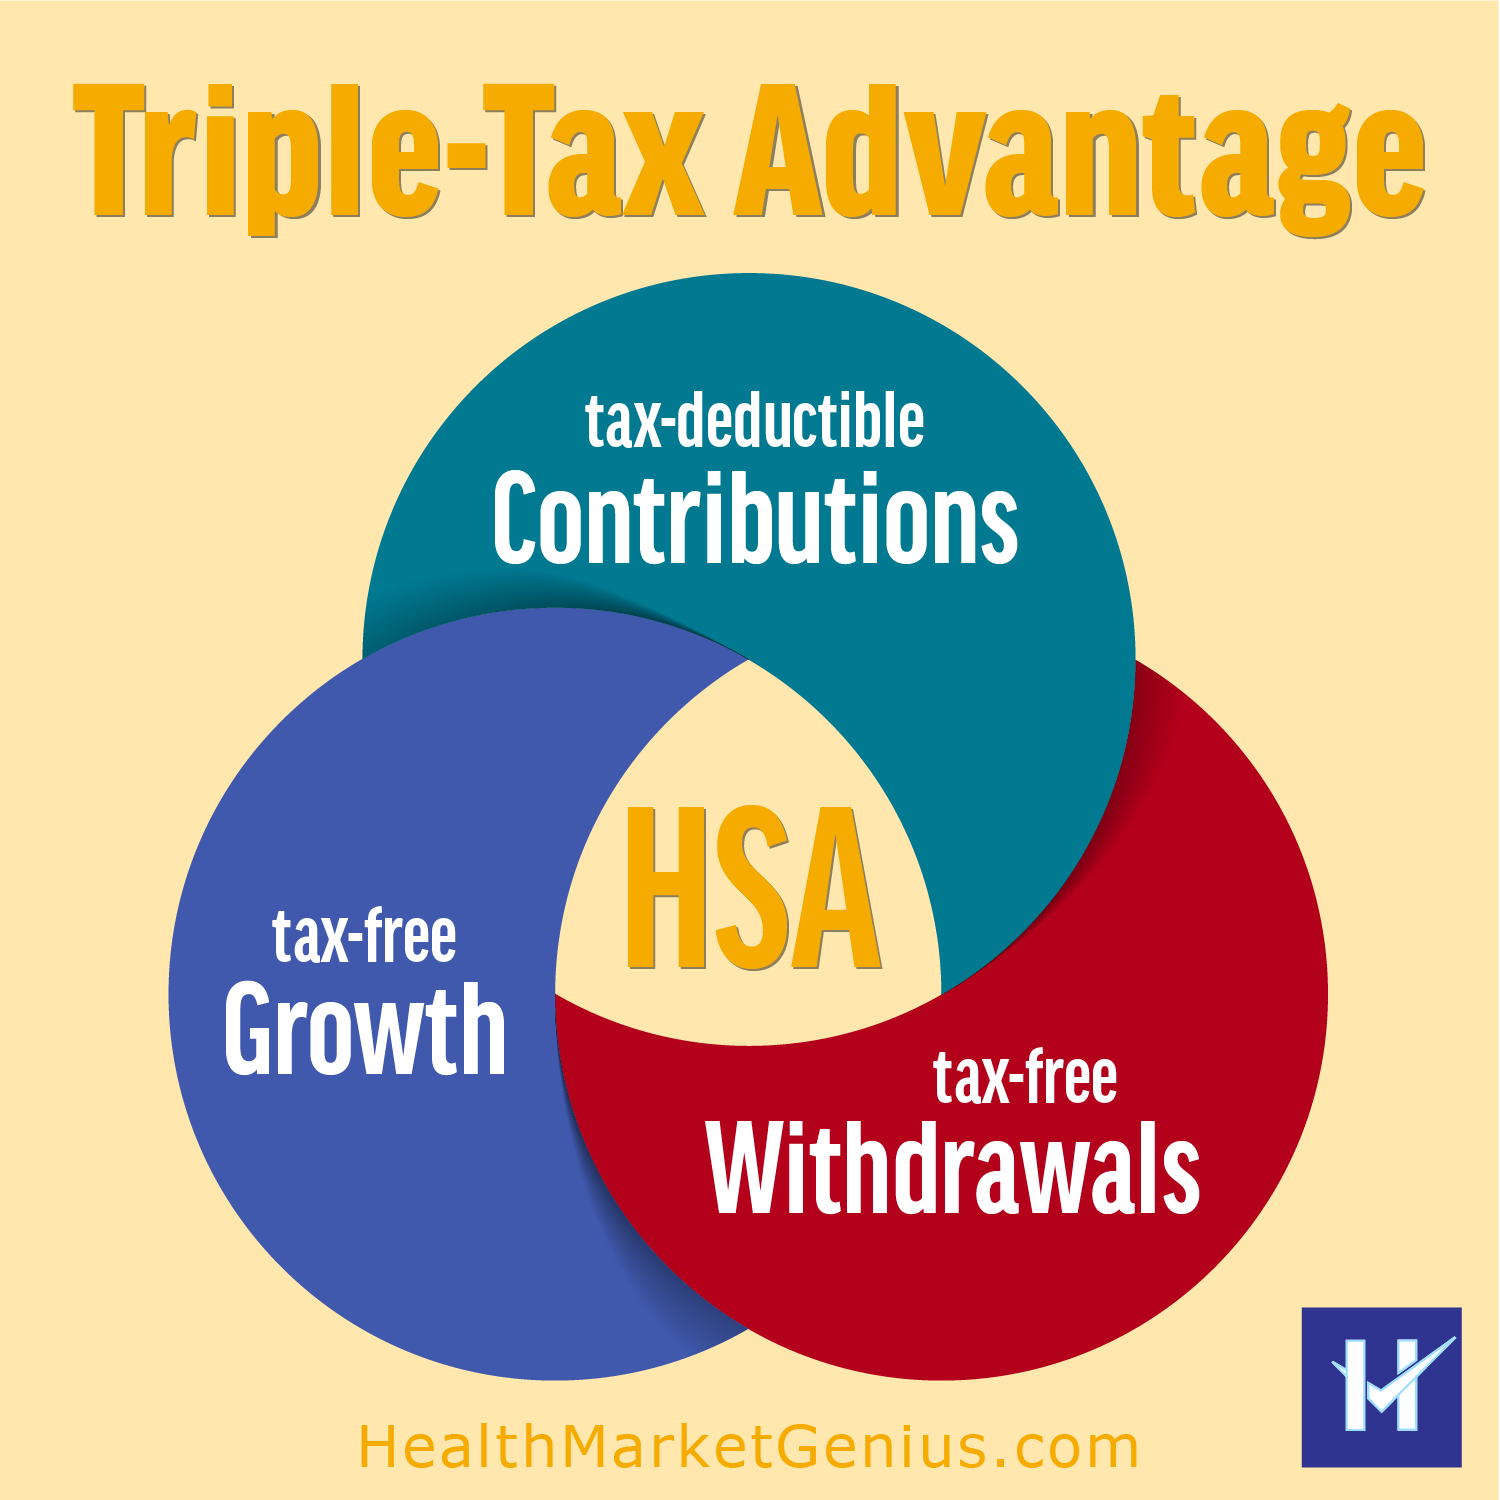
How the Triple Tax Benefit Works
This is the math of a "Smart" decision: (1) You lower your taxable income today, (2) your balance grows without being taxed, and (3) you pay for doctors or prescriptions with 100% tax-free dollars. It’s effectively a 20–30% discount on all your medical care.
Qualifying for an HSA
To get the tax breaks, you must play by the rules. You need a specific type of insurance called an HSA-eligible High Deductible Health Plan (HDHP). The "Smart Lens" advice here? Don't just look at the deductible; look at the total tax savings to see if the math works in your favor.
Bronze and Catastrophic Plans are Now HSA-Qualified
This is the best part of the 2026 law: Bronze and Catastrophic plans on the Marketplace now qualify for an HSA. This allows you to have lower monthly premiums and a high-powered tax-savings account at the same time.
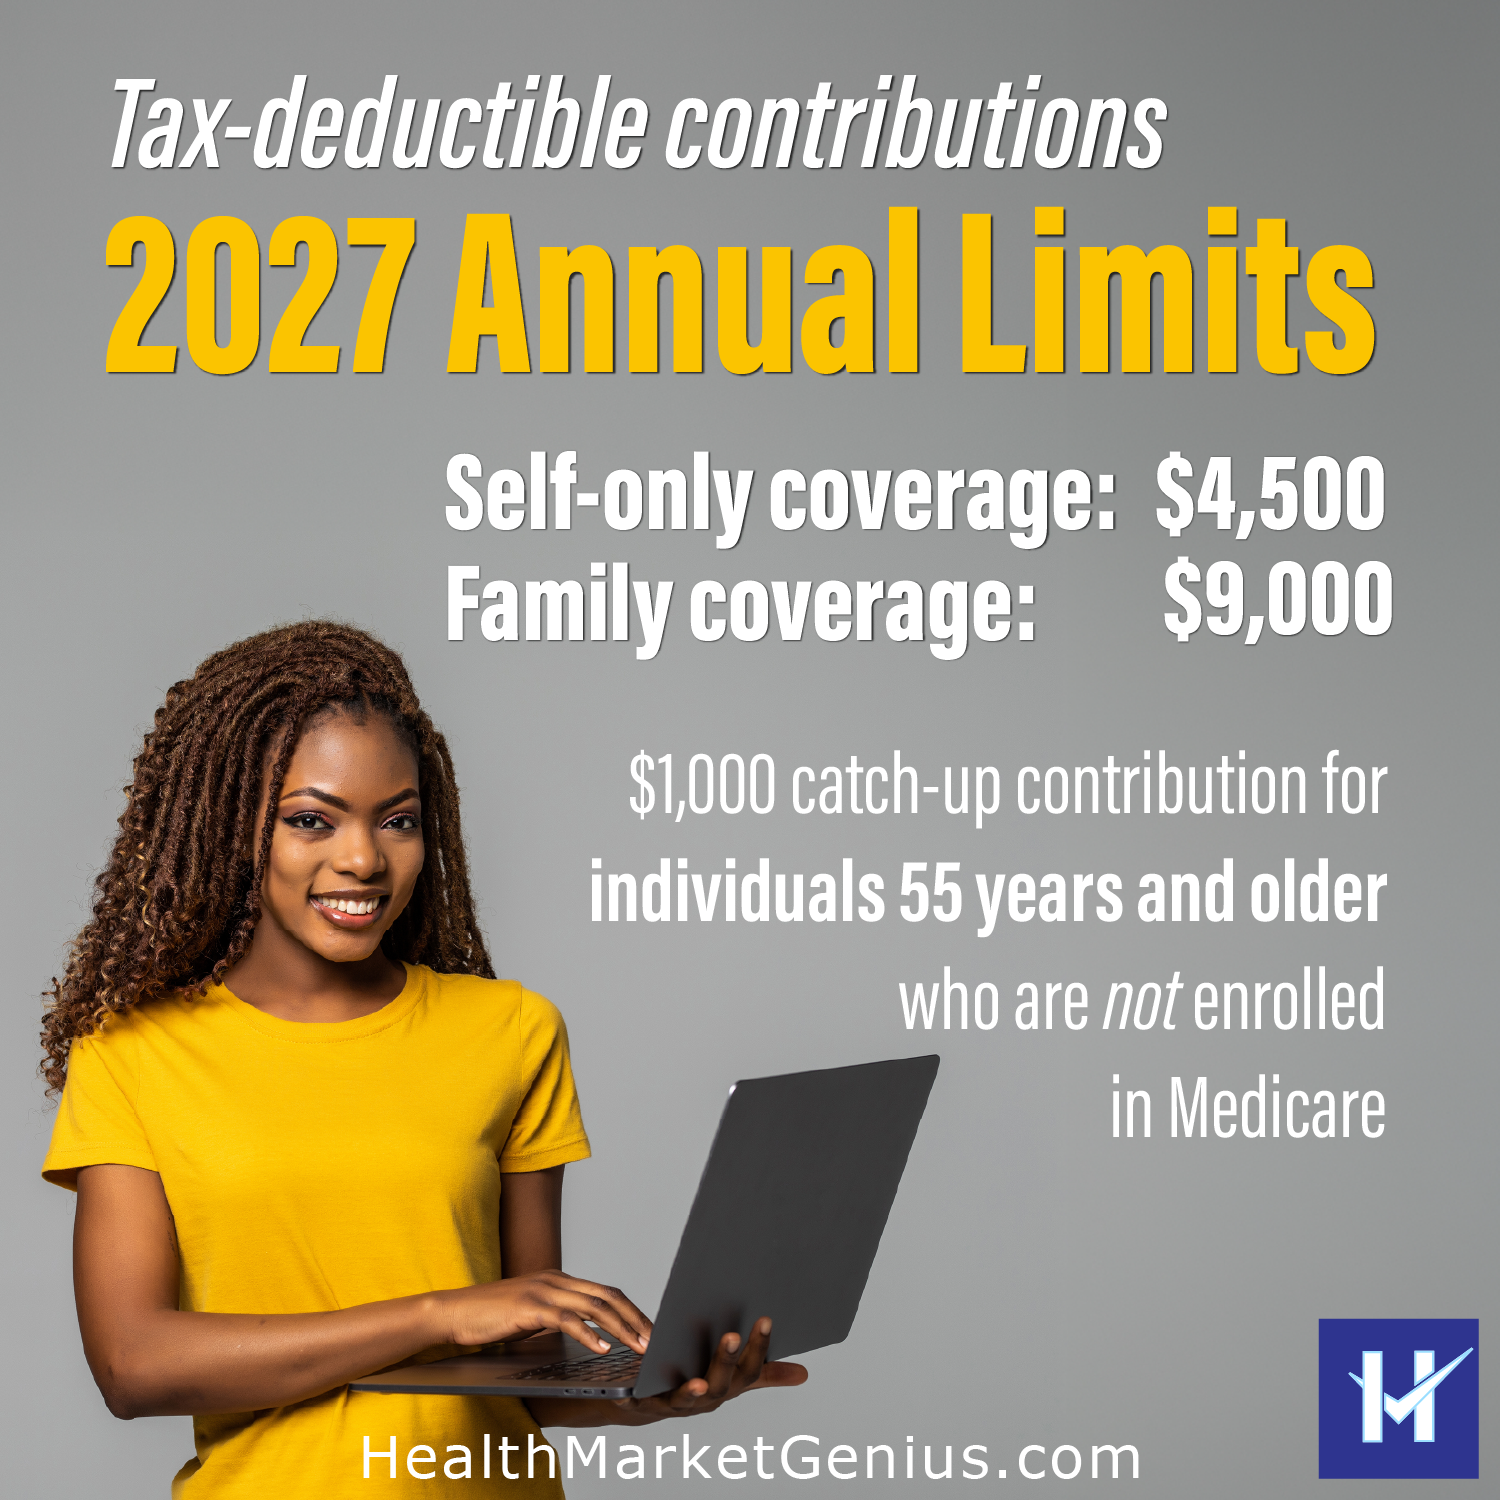
Maximize Your 2027 Savings
The 2027 limits have increased significantly. For a family, being able to shield $9,000 from taxes is a massive financial win. If you’re over 55, don't forget that extra $1,000 "catch-up"—it’s essentially free money from the IRS.
Free Money From Your Employer
If your employer offers an HSA contribution, take it! Just keep an eye on the total. Between your contributions and theirs, you cannot exceed the annual limit. We can help you calculate that "sweet spot" so you don't over-contribute.
Keep an Eye on the Contribution Deadline
Flexibility is key. You don't have to fund the whole account in January. You have until the tax-filing deadline in April of the following year to make your contributions count for the previous year. It’s a great way to lower your tax bill right before you file.
Put Our Expertise on Your Side
Understanding the new 2026 HSA rules is only half the battle; the real "Smart" move is knowing how to apply them to your specific health needs and budget.
We don’t just find you a plan—we help you build a strategy that maximizes your tax savings while protecting your family's wellness.
The Smart Lens/Health Market Genius LLC provides educational insights; always consult with a tax professional regarding your specific financial situation.