ACA Open Enrollment starts November 1st. With Marketplace subsidy eligibility tied to Federal Poverty Level (FPL) thresholds, understanding your Modified Adjusted Gross Income (MAGI) is critical. Learn how 2027 income limits apply to your household size, what happens to your subsidy if you exceed these income limits, and how pre-tax HSA contributions can lower your MAGI to protect thousands in premium tax credits.
What You Need to Know About 2027 ACA Subsidies
As we move closer to ACA Open Enrollment on November 1st, many households across NC and SC are evaluating how their income affects their health insurance coverage and monthly savings.
To help you plan, we’re addressing three essential topics that impact your 2027 subsidy eligibility and tax filing.
What is the maximum income limit for 2027 ACA Marketplace subsidies?
ACA Marketplace subsidies (Premium Tax Credits) do not use a single flat income cap for everyone. Eligibility is tied to the Federal Poverty Level (FPL) for your specific household size, with the traditional "subsidy cliff" standing at 400% of FPL.
Here is what the 400% FPL threshold looks like for four common household setups:
- Single Individual (1 person): $63,840
- Married Couple without Children (2 people): $86,560
- Married Couple with 1 Child (3 people): $109,280
- Married Couple with 2 Children (4 people): $132,000
- Single Parent with 2 Children (3 people): $109,280
If your household income is at or below the threshold for your family size, you can qualify for a subsidy to lower your monthly premium.
What happens if my income goes over the threshold by just $1?
Because the 400% FPL rule acts as a strict "cliff," earning even $1 over the limit for your household size drops your premium tax credit to $0.
- The Impact: If a family of four earns $132,001 instead of $132,000, they lose 100% of their subsidy for the entire year.
- Tax Reconciliation: When you file your federal income tax return, your actual year-end income is compared against the advance subsidies you received. Crossing the threshold means you will owe the entire advance credit back.
Because small income changes (like end-of-year bonuses or gig work) can cause a big tax surprise, tracking your annual totals is essential.
How do I calculate my MAGI for ACA health insurance?
HealthCare.gov evaluates your eligibility using Modified Adjusted Gross Income (MAGI). For most people, MAGI begins with your Adjusted Gross Income (AGI) from Form 1040 Line 11a.
To find your ACA MAGI, take your AGI and add back three specific untaxed items if you have them:
- Non-taxable Social Security benefits
- Tax-exempt interest (such as municipal bond interest)
- Untaxed foreign earned income
What happens if your MAGI estimate was too low?
If your end-of-year MAGI turns out higher than what you estimated on HealthCare.gov, you will reconcile the difference on your tax return and repay excess credits received.
Updating HealthCare.gov as soon as your income shifts mid-year prevents unexpected tax bills.
Can an HSA contribution lower my MAGI and save my subsidy?
Yes! Because pre-tax contributions to a Health Savings Account (HSA) reduce your overall Adjusted Gross Income (AGI), they directly lower your ACA MAGI.
If your estimated income is hovering right near the 400% FPL subsidy cliff (for instance, $1,500 over the limit), making an HSA contribution before the federal tax filing deadline—April 15th of the following year—lowers your MAGI back below the threshold, protecting thousands of dollars in premium tax credits.
Which plans are eligible for an HSA?
Under expanded Marketplace standards, all Bronze and Catastrophic plans are HSA-eligible, alongside specifically designated Silver and Gold High Deductible Health Plans (HDHPs).
What are the 2027 HSA contribution limits?
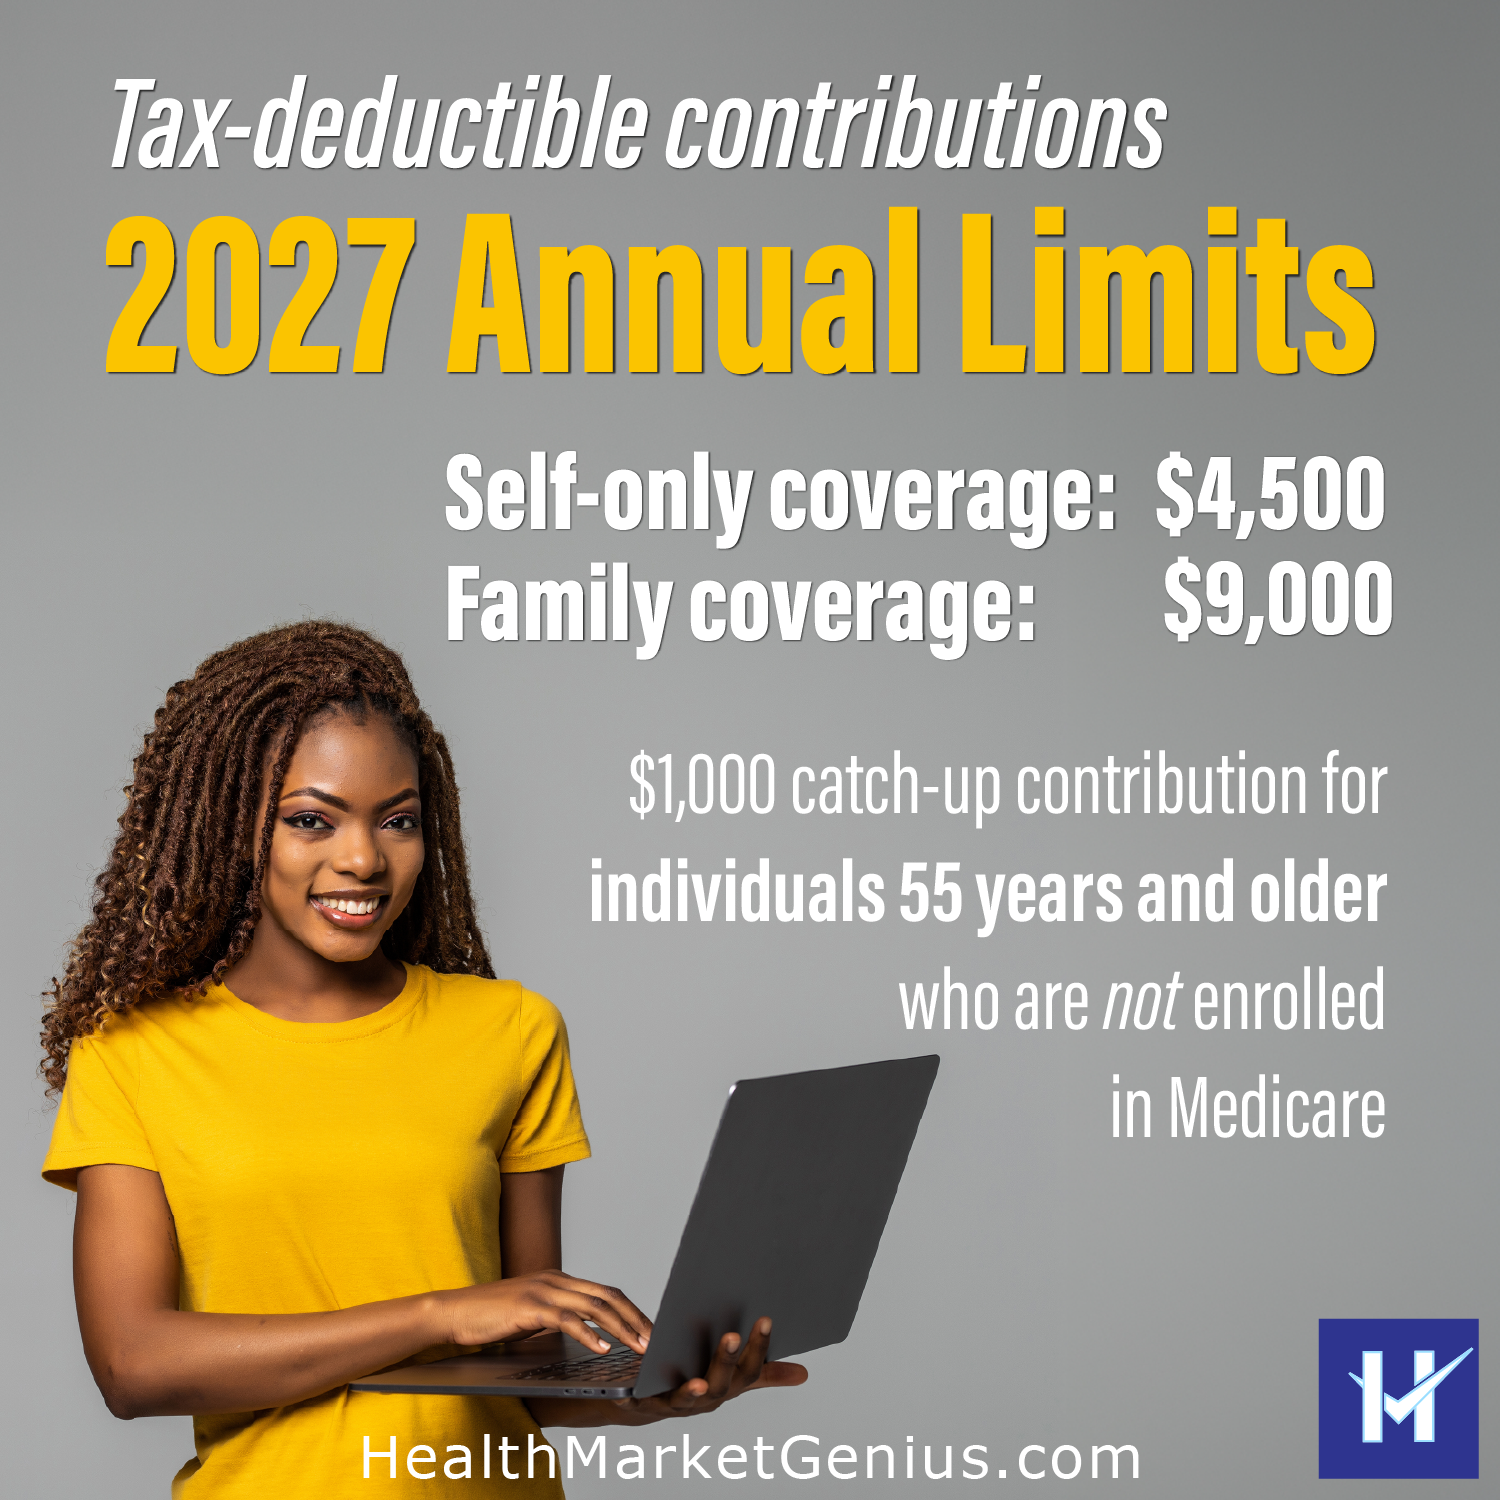
For 2027, the IRS allows individual policyholders to contribute up to $4,500 and families up to $9,000 pre-tax, with an additional $1,000 catch-up contribution available for individuals age 55 and older who are not enrolled in Medicare.
Clear Guidance for Your 2027 Health Plan
Whether you need help estimating your household MAGI, choosing an HSA-eligible Bronze plan, or verifying your subsidies in NC and SC, we are here to keep your health coverage affordable and stress-free.
Our streamlined 5-step process takes the guesswork off your shoulders, guiding you smoothly from start to finish.
If you have any questions, please don't hesitate to contact us.